Key Steps to Prepare for a VA Renovation Purchase
Understanding the Foundation of a VA Renovation Loan
Before you start looking at fixer-uppers, it pays to understand what a VA renovation loan actually requires. Unlike a standard mortgage, this product combines the purchase price of a home with the cost of repairs or improvements into a single loan. The catch is that not every renovation project qualifies, and the lender needs to see a clear plan before approving the funds. The process involves multiple parties, including appraisers, contractors, and the lender itself, all working from the same set of guidelines. For veterans planning to buy a home that needs work, knowing these requirements early can save a lot of frustration down the road.
Check Your Eligibility and Entitlement Status
The first thing to verify is your VA loan eligibility. You need a valid Certificate of Eligibility (COE) that shows you meet the service requirements set by the Department of Veterans Affairs. Beyond the basic eligibility, you also need to understand your remaining entitlement. If you currently own a home with a VA loan or have used your entitlement before, the amount available for a renovation purchase may be reduced. Contact a VA lender to request your COE and confirm your full entitlement amount. This step is straightforward but often overlooked, and it directly affects the maximum loan amount you can pursue.
Review Your Credit and Debt-to-Income Ratio
VA loans are known for flexible credit requirements, but lenders still evaluate your credit history and current debts. A credit score of at least 620 is common among VA lenders, though some may allow lower scores with compensating factors. Your debt-to-income ratio matters, too. Lenders look at your monthly debts relative to your gross monthly income. If you carry high credit card balances, auto loans, or student debt, those payments eat into the amount the lender will approve for a mortgage payment. Paying down revolving debt before you apply can improve your approval chances and increase the renovation budget the lender will allow.
Assess the Property Condition and Work Scope
The property you choose must meet minimum property requirements set by the VA. These standards ensure the home is safe, sanitary, and structurally sound. If the home fails to meet these requirements, repairs must be part of the renovation plan. This is where the work scope comes in. The work scope is a detailed list of all improvements or repairs you intend to make, including materials, labor, and costs. It must be prepared by a licensed contractor and approved by the lender before closing. When you inspect a potential property, pay attention to major systems like roofing, electrical, plumbing, and HVAC. Even if you plan cosmetic updates, the VA will require that the home be livable from day one. Make sure your contractor bid includes all necessary repairs to bring the home up to standard, not just the upgrades you want.
Get a Reliable Contractor Bid and Detailed Renovation Plans
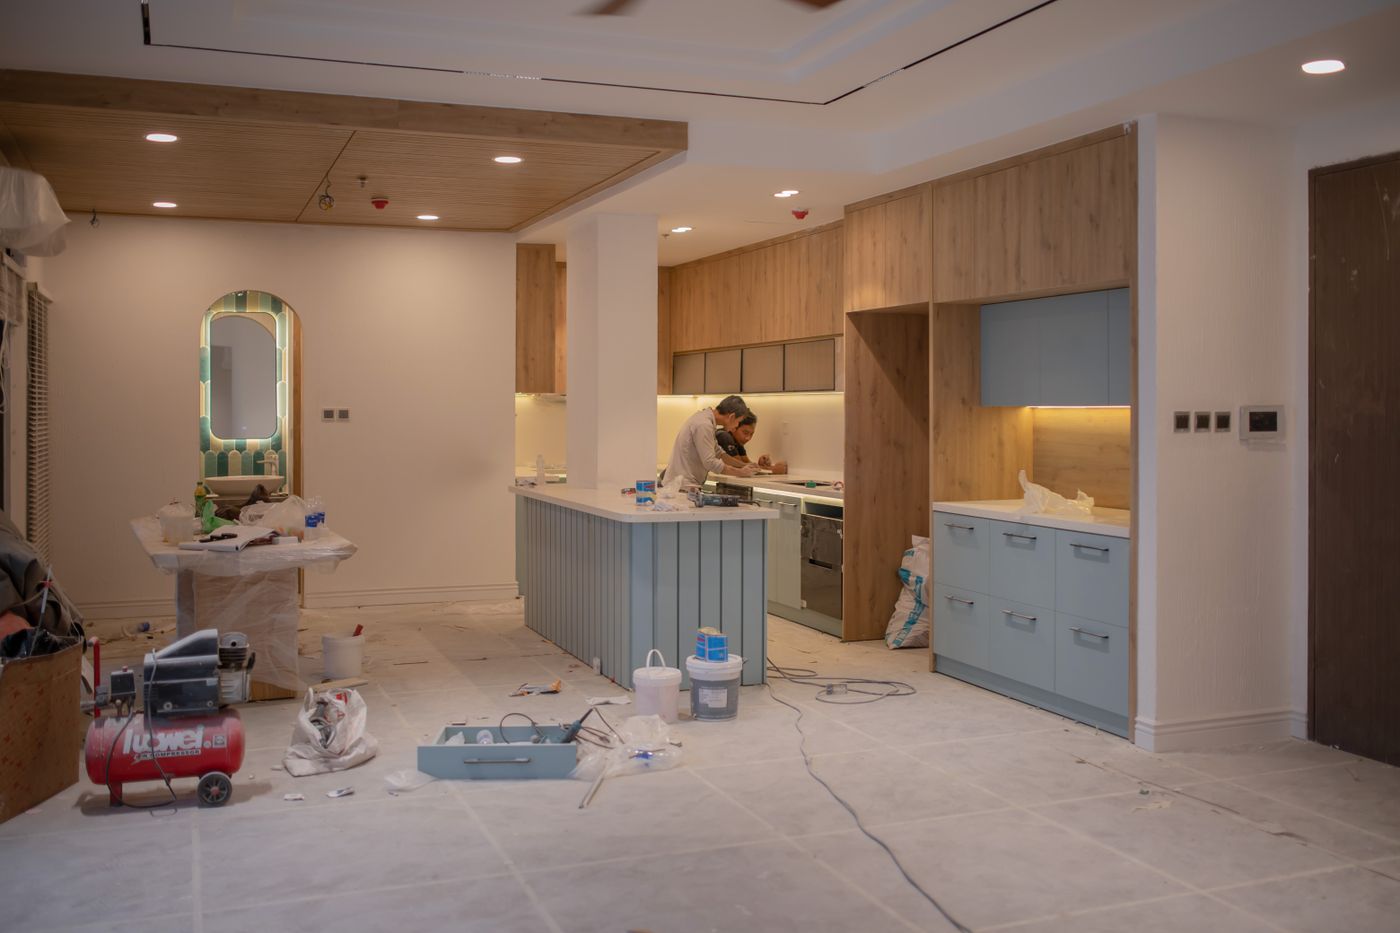
One of the more involved requirements is securing a contractor bid that the lender can work with. The bid must be itemized, showing costs for each part of the renovation, and it must come from a licensed contractor who can provide proof of insurance and bonding. The renovation plans themselves need to be clear and complete, including floor plans, specifications, and any required building permits. Lenders typically require that the contractor be approved by the VA or at least meet the lender's own standards. If you have a preferred contractor, check with your lender early to avoid delays. Some lenders maintain a list of approved contractors, while others allow you to choose, but the bid still must be detailed enough to support the loan amount.
Understand the Draw Schedule and Construction Timeline
Once you close on the loan, the renovation money is not handed over in one lump sum. Instead, it is disbursed through a draw schedule. The contractor completes a phase of the work, an inspection is done to verify completion, and then the lender releases the next payment. This process protects both you and the lender, but it requires careful planning. You need a realistic construction timeline that accounts for weather, material availability, and contractor scheduling. Delays can push back the draw schedule, which may affect your temporary living arrangements if you plan to move in after the work is done. Discuss the timeline with your contractor before you finalize the bid, and build in a project contingency for unexpected issues. A common buffer is 10-15% of the total renovation cost, but check with your lender on what they allow.
Prepare for Inspections and Approvals
Inspections are a regular part of the renovation process under a VA renovation loan. An appraiser reviews the initial property condition and the proposed work scope before closing. After closing, each phase of construction triggers an inspection to confirm the work matches the approved plans. The lender may use a staff appraiser or a third-party inspector. Make sure your contractor is prepared for these inspections and that the work scope includes enough detail so there is no confusion about what is expected. If the inspector finds incomplete work, the draw payment can be delayed, which stops the job. Keeping open communication between you, the contractor, and the lender helps avoid these hiccups.

Plan for Your Own Financial Contingency
Even with a thorough contractor bid and a solid work scope, unexpected costs can arise. The VA renovation loan does allow for a contingency reserve within the loan amount, but it is limited. You should have your own savings to cover any overruns that the lender will not finance. Think about costs like temporary housing if you cannot live in the home during construction, storage for your belongings, or upgraded finishes that you decide to add after the loan closes. The loan is based on the approved plans, so any changes after closing require lender approval and can be complicated. It is easier to include everything you want in the initial work scope, even if you plan to do some work later. The VA renovation loan requires that all improvements be completed within a set timeframe, usually six months, so keep that in mind when planning your project.
Coordinate with Your Lender Early
Not all lenders handle VA renovation loans the same way. Some have overlays, which are additional requirements beyond the basic VA guidelines. For example, a lender might require a higher credit score, a larger contingency reserve, or a specific contractor licensing standard. Before you make an offer on a property, talk to your lender about their specific VA renovation loan requirements. Ask about their draw schedule process, their approved contractor list, and any documentation they need upfront. When you are planning a lender-ready renovation, the goal is to have all your paperwork in order so the lender can move quickly. Delays often come from missing contractor bids, incomplete renovation plans, or unclear work scopes. The more organized you are, the smoother the process will be.
Review the Building Permit Requirements
Most significant renovations require a building permit from the local municipality. The permit ensures that the work meets local building codes and safety standards. The VA renovation loan does not require the permit itself, but the lender will need to see that the contractor has obtained the necessary permits before work begins. If the contractor's bid does not include permit fees, you may need to pay those separately or adjust the loan amount. Check with your contractor early to understand what permits are needed and how long they take to issue. In some areas, the permit process can add weeks to the construction timeline. Factor that into your plans so you are not caught off guard.
Final Checks Before You Submit Your Application
Before you submit your loan application, run through this list one more time. Confirm your COE and entitlement status. Gather your financial documents, including pay stubs, tax returns, and bank statements. Have your contractor bid and renovation plans ready, with a clear work scope and an itemized cost breakdown. Verify that the contractor is licensed, insured, and willing to work with the lender's draw schedule. Understand the construction timeline and have a contingency plan for delays. When you are planning a lender-ready renovation, every piece of documentation you provide upfront reduces the chance of a surprise request later. Speak with your lender about their specific overlays and make sure you meet those requirements before you find a property. With a solid preapplication checklist, you can move forward with confidence, knowing that you have addressed the major hurdles before they become problems.